Key takeaways
- Record what you observed separately from conclusions about the cause.
- Keep the plumber's written findings with your room photos.
- Treat emergency mitigation as its own chapter with logs and invoices.
- Know which policy questions remain open: cause, timing and resulting damage.
Separate observations from conclusions
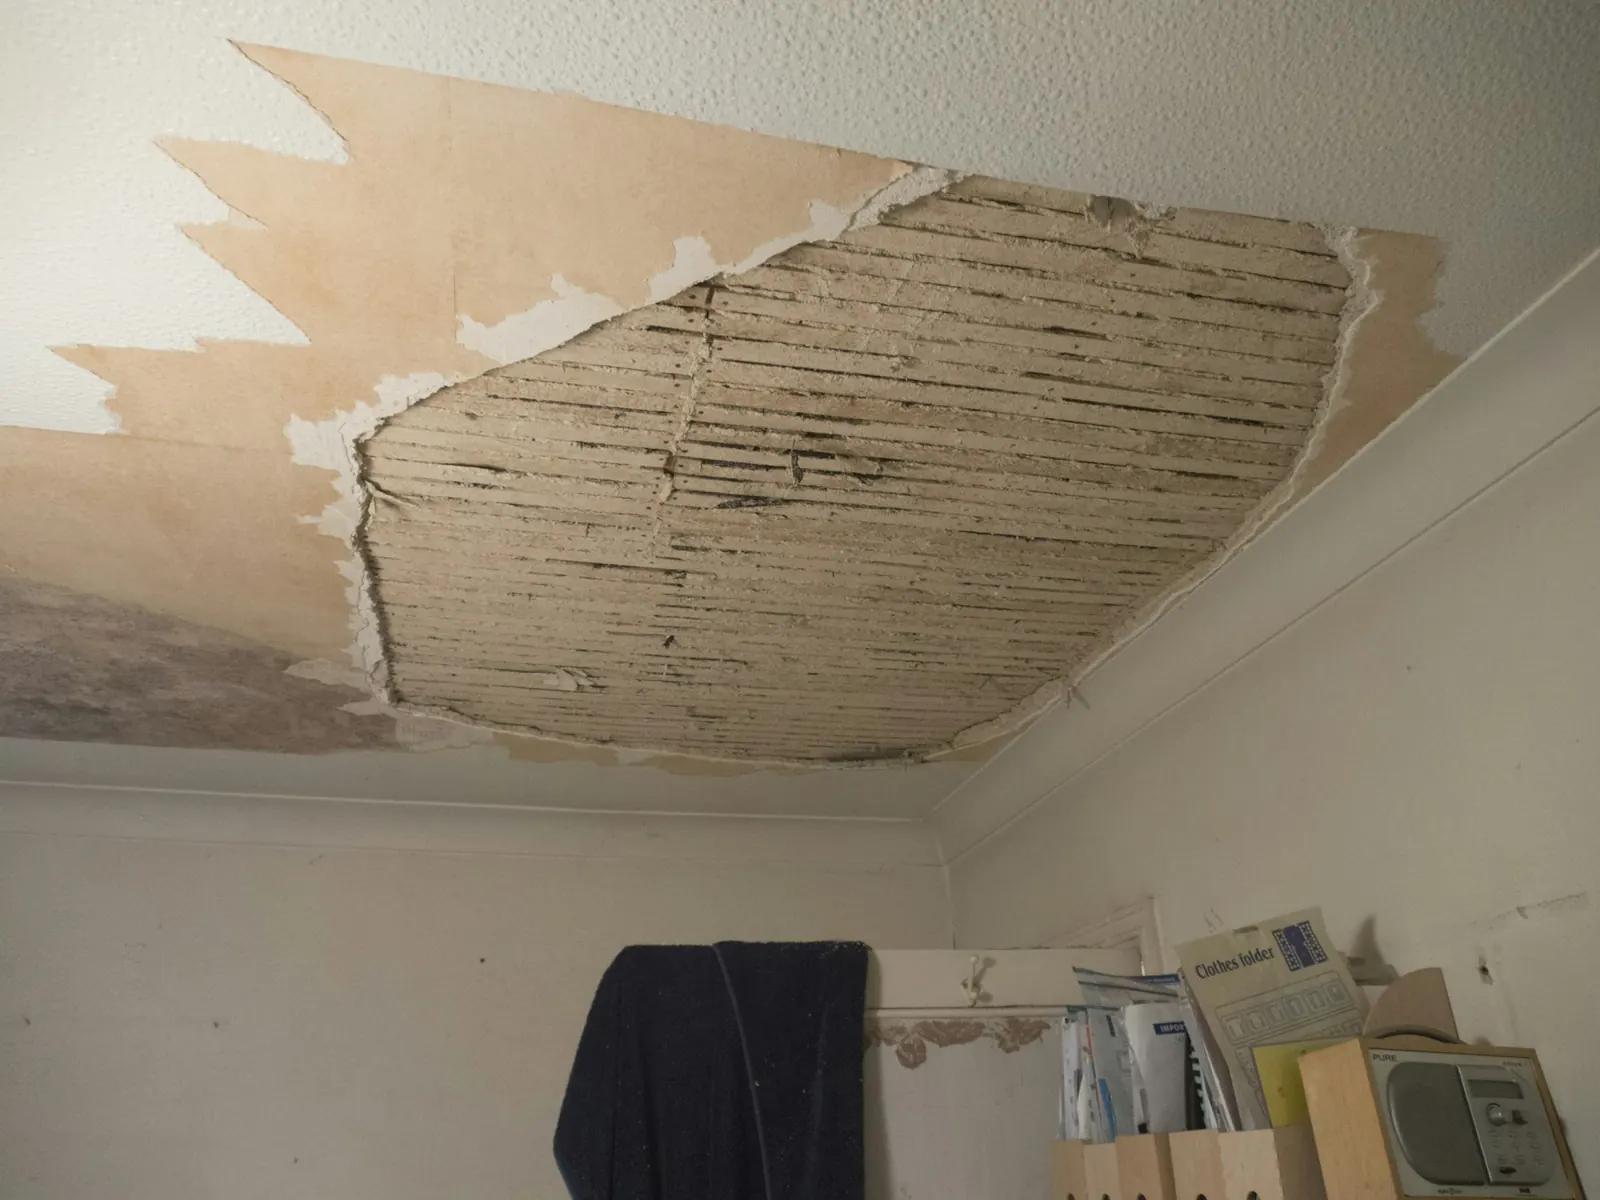
Begin with what you personally noticed: the date, time, location and visible condition. If someone else discovered the water, note who it was and save their description. Avoid assigning a start time to a leak unless you have evidence for it.
A timeline might say the kitchen floor was dry the evening before and standing water was found the next morning. That is an observation. The cause may require a plumber or leak-detection specialist to determine, especially with slab foundations, which are common in The Colony.
Keep the source report with the room records
Ask the professional who finds the source to give you a written description of what they found and what they repaired. Keep that report with the invoice, photographs and related correspondence. A repair invoice and a cause assessment serve different purposes, and one may not fully explain the other.
Document each affected room separately. Record which surfaces and belongings got wet and when photos were taken. If furniture or contents are moved during cleanup, note where they were. That helps everyone connect the record to the property as it was found.
Document urgent mitigation as its own chapter
Safety and reasonable steps to prevent further damage come first. Keep contact details for anyone who performs emergency work, along with the work authorization and invoice. Ask for moisture readings, drying logs and equipment lists that show which areas were treated.
- Photograph conditions before mitigation begins, if it is safe.
- Label photos as before, during and after only when those labels are accurate.
- Keep removed materials, or photos of them, until they have been documented.
- Never recreate or stage a condition to fill a gap in the record.
Ask which policy questions remain open
Water losses are not all treated the same. Texas Department of Insurance guidance distinguishes sudden and accidental water release from continuous leakage and flooding. Your own policy language and the cause of the loss still need review.
Keep a running list of open questions. What caused the release? What does the carrier need to evaluate it? Which estimate items cover the resulting damage? Who is preparing the remaining documentation?
Before sending a large set of files, prepare a one-page index so each report is easy to find. If you would like help, The Colony Public Adjuster offers a free claim review, and our water damage claim service explains how we help.
Frequently asked questions
How long does a water damage claim take in Texas?
It varies with the size of the loss, the investigation needed and how quickly documents are provided. Texas prompt-payment rules set deadlines for insurer responses once they receive the items they requested. Try our Texas claim deadline calculator.
Can mold from a leak be covered?
Mold coverage is often limited or excluded, though resulting mold from a covered water event may be addressed in some policies. Read your policy's mold provisions and document moisture early.
Continue preparing. Use our free claim tools or request a free review from The Colony Public Adjuster to talk through your next step.
Further reading: Texas Department of Insurance: Homeowners insurance guide. This article is general educational information from The Colony Public Adjuster. Your policy and circumstances govern your claim, and this is not legal advice.