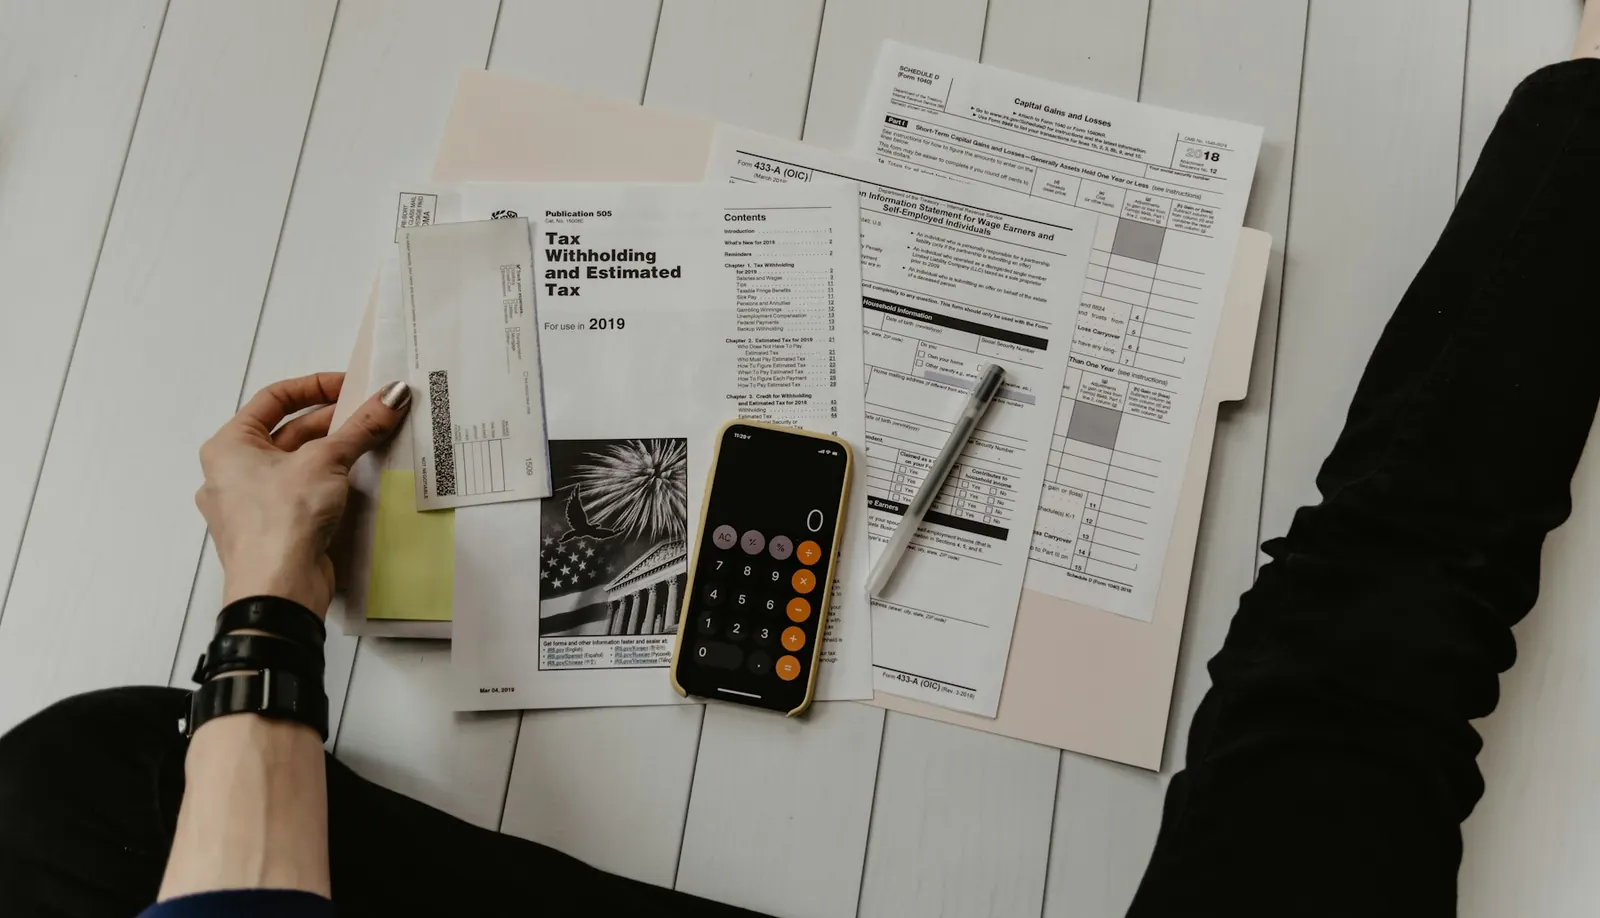
How to read a property claim estimate without getting lost
An estimate is easier to understand when you separate the repair scope from the payment math. Start with the work described, then follow the numbers.
Read the guide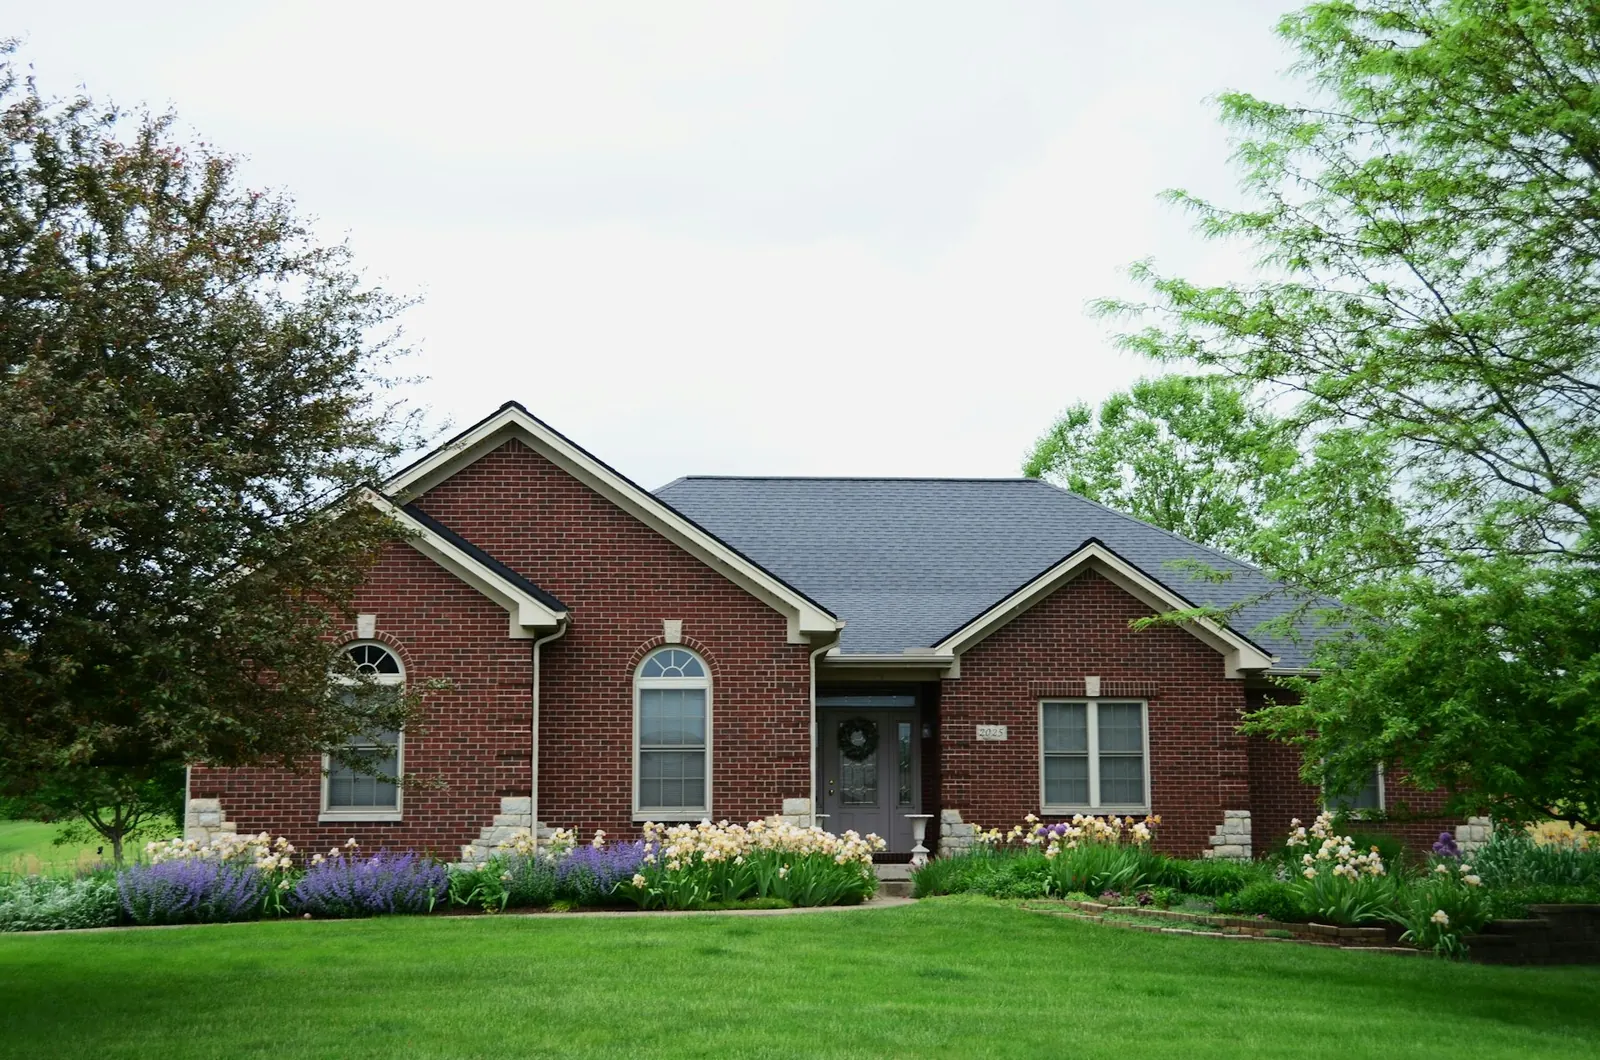
Homes, townhomes, rental houses and everything inside them. The Colony Public Adjuster represents homeowners and landlords in The Colony through the full property claim.
A homeowner claim can involve the dwelling, detached structures such as fences and sheds, personal property, and additional living expenses. Each part of the policy has its own limits, deductibles and conditions, and the evidence needed for each is different.
From a newer build in Austin Ranch to an established home near Stewart Creek Park, The Colony Public Adjuster starts with the facts of your property. We organize the damage record, compare estimates line by line and help you understand which questions to raise under your specific policy.
Discuss your residential claim
A strong residential property claim is built from specific, well-organized evidence. Here is what we gather and present on your behalf.
Line items, quantities or labor may be missing. We compare scopes side by side and document the gaps.
Withheld depreciation and how to recover it can be confusing. We explain the numbers and the steps involved.
Repairs may require work to meet current building codes. We look at whether your policy includes ordinance or law coverage.
When a claim stalls, an organized file and clear follow-up can help move it forward.
Make a simple room list. Keep photos and receipts in folders named for each room, and record when the damage was first discovered. Gather your declarations page and any letters or estimates from the insurer.
Representation, services and fees are set out in a written agreement. Coverage and outcomes depend on your policy and the facts of the loss.
Yes. Landlords and owners of single-family rentals can be represented for damage to the building and their own property. Tenants' belongings fall under the tenant's own policy.
Not always. For a straightforward loss you may be comfortable handling it yourself. We will tell you honestly during the free review if representation is unlikely to help.
Often, yes. Depending on your policy and timelines, a supplemental claim or a request for reconsideration may be possible. Bring the estimate and payment letter to the review.
Tell us what happened. We review the claim status, the policy and your concerns, and explain whether representation is likely to help. No cost, no obligation.
We inspect the property and organize photographs, measurements, moisture readings and 3D imaging where useful, building a complete record of the loss.
We prepare a detailed repair estimate in industry-standard software such as Xactimate and compile the photos, reports and records that support it.
We present the claim, answer the carrier's requests and follow up on missed or undervalued items, keeping you informed throughout.
An estimate is easier to understand when you separate the repair scope from the payment math. Start with the work described, then follow the numbers.
Read the guideAn inventory does not have to be perfect to be useful. Start with one room and build a record another person could understand without you there.
Read the guideWind & hail damage · Water damage · Fire & smoke damage
All servicesTalk with The Colony Public Adjuster about the damage, the paperwork and your next step. The first review is free and there is no obligation.